 Your Wealth May Be Lost to Your Own Family: The ₹1 Lakh Crore Wake-Up Call India Cannot Ignore
You spent 30 or 40 years earning money, building assets and securing your family’s future. But have you ever asked yourself one simple question: If something happens to me tomorrow, will my family know where all my money is and how to claim it?
Imagine a husband who spent his entire working life earning money for his wife and children.
He maintained bank accounts, purchased life insurance, invested in mutual funds, opened fixed deposits, bought shares and accumulated retirement savings.
He believed he had fulfilled his responsibility towards his family.
But there was one thing he never did.
He never properly informed his family about his financial assets. He never updated nominations in several financial accounts. He never maintained a consolidated record of his investments.
One day, he was no longer there.
His family knew he had worked hard and accumulated wealth. But they did not know how much money he had, where it was invested, which institutions held it or how to claim it.
The money existed.
The family needed it.
But accessing it became a struggle.
Unfortunately, this is not merely an imaginary situation. It is a financial reality for thousands of Indian families.
India’s hidden financial wealth: The numbers are alarming
We often discuss India’s growing economy, increasing household savings, rising mutual fund investments and expanding financial markets.
But there is another side of India’s financial story that deserves our attention.
A significant amount of money belonging to ordinary Indian citizens remains unclaimed in the financial system.
Consider these figures:
- Unclaimed bank deposits: ₹86,917 crore
As of June 30, 2026, banks had transferred approximately ₹86,917 crore in unclaimed balances to the Reserve Bank of India’s Depositor Education and Awareness (DEA) Fund.
These include savings and current accounts that have remained unoperated for ten years or more and term deposits that have remained unclaimed beyond the prescribed period.
Think about this number.
₹86,917 crore is not money that appeared from nowhere. It represents savings accumulated by individuals and families through years of hard work.
- Unclaimed insurance money: ₹20,062 crore
According to IRDAI’s Annual Report for FY 2023-24, approximately ₹20,062 crore was lying unclaimed with insurance companies as of March 31, 2024.
Behind every insurance policy, there may be a family that was supposed to receive financial protection.
Insurance is purchased to protect loved ones when the earning member is no longer around.
But what happens when the family does not know about the policy or does not initiate the claim?
The very financial protection purchased for the family may remain unclaimed.
- Unclaimed mutual fund investments: ₹3,811 crore
According to SEBI’s Annual Report 2025-26, unclaimed mutual fund dividend and redemption amounts stood at approximately ₹3,811 crore as of March 31, 2026.
Mutual funds are increasingly becoming part of Indian household portfolios.
People invest through SIPs, lump-sum investments and retirement-oriented strategies.
But how many investors maintain proper records and ensure that their family members know about these investments?
- The government’s nationwide recovery effort
The Government of India conducted a nationwide campaign, ‘Your Money, Your Right’, across 748 districts between October 2025 and February 2026.
The campaign helped return approximately ₹5,777 crore through 22.95 lakh claims.
This is encouraging.
But it also raises an uncomfortable question.
If so much money has already been recovered, how much more remains undiscovered by the families who rightfully own it?
These figures relate to different reporting dates and categories. They should not simply be added together as one consolidated current figure. However, they clearly demonstrate the scale of the problem.
Why does money become unclaimed?
Most people assume that their family will automatically receive everything they own after their death.
Unfortunately, financial institutions cannot always identify the rightful claimant without information and appropriate documentation.
There are several reasons behind this problem.
First, the family does not know about the investments.
A husband may have opened multiple bank accounts during his career. A wife may have purchased insurance policies years ago. Parents may have invested in mutual funds or fixed deposits without informing their children.
When the account holder dies, family members may not even know these assets exist.
Second, nomination is ignored.
Many people open bank accounts, purchase insurance policies or start mutual fund investments but leave the nomination section blank.
Some simply forget.
Others postpone it, thinking they will complete the formalities later.
Some do not understand its importance.
Unfortunately, later may be too late.
Third, financial records are scattered.
One investment may be with a bank, another with an insurance company, another with a mutual fund house and another with a different financial institution.
There may be old folio numbers, outdated mobile numbers, changed email addresses and missing documents.
The family is left trying to connect the dots during an already difficult emotional period.
Fourth, there is no family financial communication.
In many Indian households, one person manages almost everything related to money.
The spouse and children may know that investments exist, but they do not know the details.
We discuss our children’s education, marriage, home purchase and retirement.
But we rarely discuss where our money is kept and how our family can access it.
Nomination is not a formality. It is a family responsibility.
Let me ask you a few questions.
- Have you nominated someone in every bank account?
- Have you updated the nominee in your mutual fund folios?
- Have you checked the nomination details in your life insurance policies?
- Have you reviewed nominations in your demat account, shares, fixed deposits and other financial investments?
- Have you informed your spouse about these nominations?
If you cannot confidently answer these questions, it is time to review your financial records.
Nomination is an important mechanism that helps financial institutions identify the person authorised to receive or claim assets under the applicable rules.
However, there is an important distinction: a nominee is not automatically the ultimate legal owner of every asset. The rights of legal heirs and succession laws must also be considered. Nomination helps facilitate the claim process, but it does not replace proper estate planning.
Therefore, nomination and succession planning should go together.
Do not assume that writing someone’s name in a nomination form solves every inheritance-related issue.
Five actions every Indian family should take today
Financial awareness must lead to action. Here are five practical steps every earning individual and family should complete.
- Review every financial nomination.
Prepare a list of your bank accounts, fixed deposits, mutual fund folios, insurance policies, demat accounts and other financial assets.
Check whether nominations exist and whether the details are current.
If you have multiple investments with different institutions, review each one separately.
Do not assume that nominating someone in one account automatically covers all your other investments.
- Prepare a consolidated family financial record.
Maintain one secure document containing details of all your financial assets.
Include the institution’s name, account or folio reference, investment type, relevant contact details and nomination status.
This document should help your family understand where the assets are located.
Do not write passwords, PINs or sensitive access credentials in an unsecured document.
- Talk to your spouse and family.
Your spouse should know where the investments are maintained.
Your adult children should understand whom to contact when necessary.
You do not need to disclose every financial detail to everyone. But the responsible family members should know how to locate the records and initiate the claim process.
Silence about money is not always a sign of financial discipline. Sometimes, it creates unnecessary difficulties for the people we love.
- Review your financial information every year.
Life changes.
You may open new accounts, purchase insurance, change your address, update your mobile number or make additional investments.
Review your nominations and family financial records at least once a year.
Treat this as an essential part of your annual financial health check-up.
- Check for old and forgotten financial assets.
If you suspect that you or a deceased family member has unclaimed investments, use the appropriate official platforms:
- Bank deposits: RBI’s UDGAM portal.
- Insurance: IRDAI’s Bima Bharosa portal.
- Mutual funds: SEBI’s MITRA platform.
Visit the respective regulator’s official website to access these services and follow the prescribed claim procedure.
Remember, unclaimed money does not automatically mean lost money. Eligible rightful claimants can approach the relevant institution and submit the necessary documents to recover it.
A message to every earning member of an Indian family
We want every working professional, business owner, government employee, private-sector employee, self-employed individual and retired person to think about this.
You may have spent your entire life earning money.
You may have sacrificed holidays, personal comforts and family time to build financial security.
You may have invested regularly for your children’s education, purchased insurance to protect your spouse and accumulated retirement savings to enjoy a peaceful old age.
But have you made sure that your family can actually identify and access these assets when you are not there?
Financial responsibility does not end with creating wealth.
It also includes making that wealth accessible to the people who are legally entitled to receive it.
Your family should not have to search through old files, visit multiple financial institutions, contact distant relatives or struggle with documentation while dealing with the emotional loss of a loved one.
The money you leave behind should provide security, not create confusion.
A little preparation today can save your family months or even years of unnecessary difficulty tomorrow.
Financial planning is not only about growing wealth. It is about protecting your family’s financial future.
At SmartMantra, we believe that financial planning goes beyond selecting investments, starting SIPs or building a retirement corpus.
It is about understanding the complete financial life of a family.
- How much wealth are you creating?
- What financial risks are you protecting against?
- Are your investments aligned with your life goals?
- Are your nominations updated?
- Does your family know where your financial assets are?
- And most importantly, will your wealth serve its intended purpose even when you are no longer around?
These are not uncomfortable questions. They are responsible questions.
India is becoming a financially aware and investment-oriented nation. But financial awareness must go beyond knowing about returns, SIPs, mutual funds and stock markets.
We must also learn about nomination, documentation, succession planning and intergenerational wealth transfer.
Let us make one promise to ourselves today: We will not allow our lifetime of savings to become an unknown financial burden for our families.
Take 30 minutes this weekend.
Review your nominations. Prepare your family asset list. Inform your spouse. Organise your financial documents.
And encourage your parents, siblings, relatives and friends to do the same.
Because the greatest financial gift you can leave behind is not just money.
It is the certainty that your family will know where it is, how to claim it and how to use it.
You worked hard to create your wealth. Take responsibility for ensuring that it reaches the right hands.
Keep moving towards financial prosperity and peace of mind.
About the Author
RUPAKUMAR PRADHAN, CFP®, CWM®
Chief Financial Planner & Founder, SmartMantra Financial Services Pvt. Ltd. | HappyMoney Coach | Author of JOYFUL RETIREMENT
Rupakumar Pradhan is a CERTIFIED FINANCIAL PLANNER® and CHARTERED WEALTH MANAGER® with 28 years of experience in financial planning and wealth management.
Through his professional practice, writing, teaching and financial education initiatives, he helps individuals, families, professionals, business owners and NRIs make informed financial decisions and work towards financial prosperity and peace of mind.
His philosophy is simple: Financial planning is not just about creating wealth. It is about creating a life with financial confidence, security and peace of mind.
He believes in helping people move towards their HappyMoney Zone.
Connect with Rupakumar:
Personal website: https://www.rupakumarpradhan.com
Professional contact: https://www.rupakumarpradhan.com/contact/
Learn about SmartMantra: https://smartmantra.in
SmartMantra Financial Services Pvt. Ltd.
Future, Designed Around You.
SmartMantra is a Bhubaneswar-based financial planning and wealth management firm committed to helping individuals and families achieve their financial goals through structured financial planning and personalised guidance.
An AMFI Registered Mutual Fund Distributor | ARN-167331.
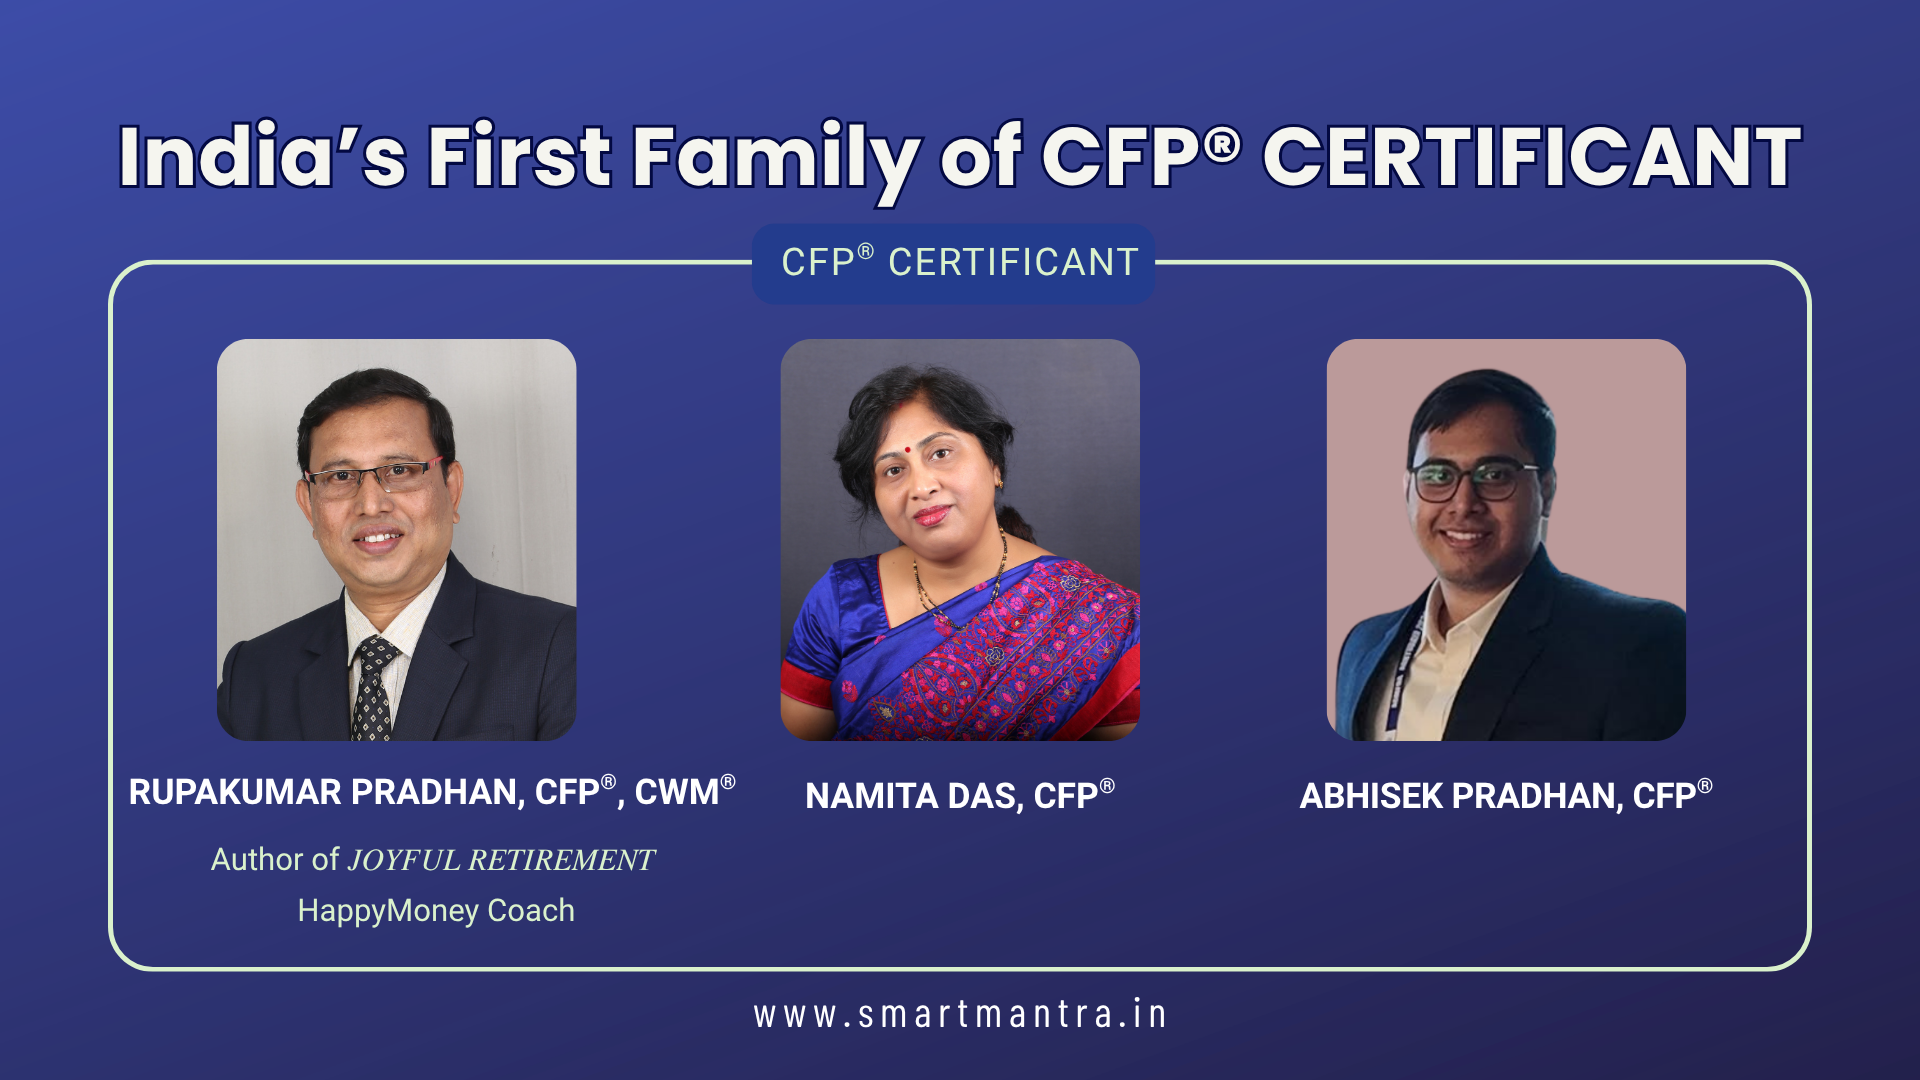
India’s First Family of CFP® Certificant
Rupakumar Pradhan, CFP®, CWM® | Namita Das, CFP® | Abhisek Pradhan, CFP®
A family united by a shared commitment to financial planning, professional learning and financial empowerment.
Keep moving towards a financially peaceful life!
Disclaimer: This article is intended for general educational and informational purposes only. It should not be construed as personalised financial, investment, insurance, tax or legal advice. Financial decisions should be made after considering individual circumstances, financial objectives and risk tolerance. Where applicable, mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing.